Commtrac Software
Product 03 of 04
Account to account point of sale
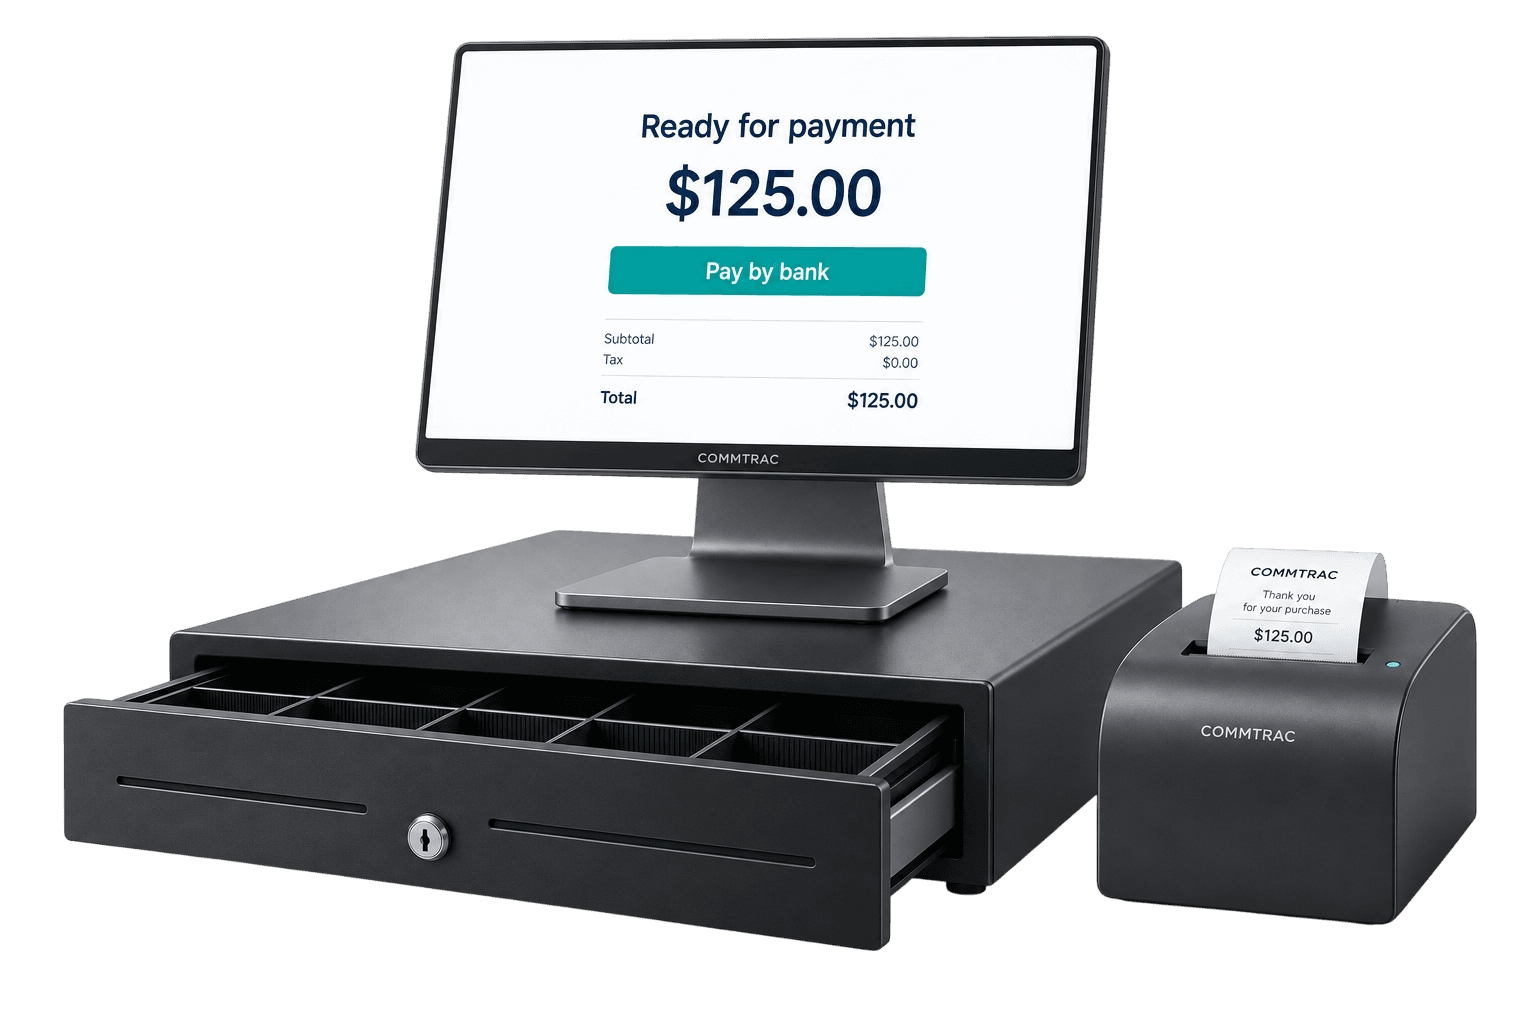
Commtrac POS
A biometrically authenticated terminal that settles every sale account to account over the domestic real time rail, straight into the bank account the business already holds. No card network, no processor, no percentage of the ticket.
Scheduled release: Q1 2028. The specification is published ahead of availability.
Reference
At a glance
Commercial terms
A flat fee a sale. Never a percentage of the ticket.
Cents per settlement, whatever the ticket
Each sale settles for a flat fee measured in cents. The same fee on a coffee and on a banquet, with no interchange, no assessments, and no processor margin.
A flat monthly rate per terminal
Terminals carry one fixed monthly rate. Commtrac Clearing ships on every terminal at no additional charge.
More than ninety nine percent below the card route
On a typical ticket the card route takes close to three percent of the sale. Commtrac POS takes cents, and no volume tier is negotiated over the merchant.
How terms are set
Terms are set with the Commtrac team against an institution’s volumes, rails, and deployment.
Speak with the Commtrac teamThe problem
Every sale pays the middlemen first.
A card sale pays a queue of intermediaries before it pays the merchant. Interchange, network assessments and processor margin are taken as a percentage of every ticket, and for a business running single digit margins those points are not a cost line. They are a silent partner.
Then the merchant waits for its own money. Card settlement batches on the processor's schedule, lands days later, and sits in an account the processor controls, exposed to holds, rolling reserves and disputes long after the customer went home happy.
Card railsettlement of a 100.00 bill
Commtrac POSthe same bill
The same bill, settled twice. For a merchant running three points of margin, the 2.88 the middlemen no longer take is not a discount on costs. Applied to every ticket, it is close to double the annual profit.
The solution
Account to account. Nothing in between.
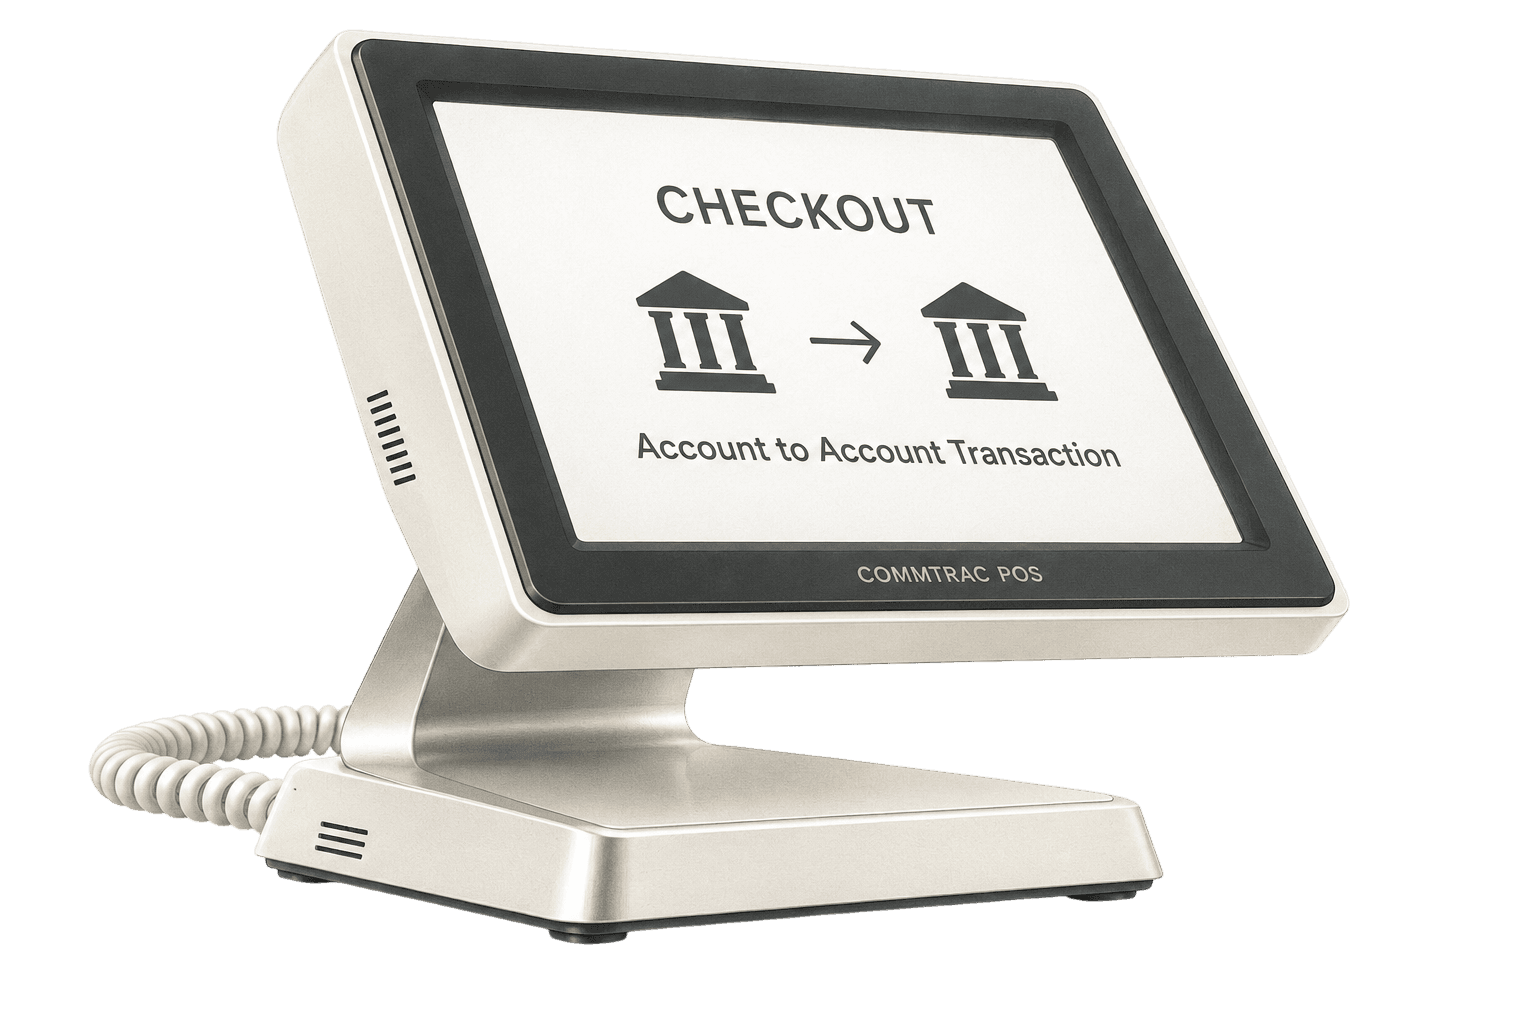
Commtrac POS is a biometrically authenticated terminal that moves a sale from the customer's bank account to the merchant's over the domestic real time rail. No card network, no acquirer, no processor custody. The customer authenticates, the payment initiates, and because the rail is irreversible the merchant can treat the sale as cleared the moment it moves.
The terminal
A payment in the time it takes to approve
The customer authenticates with biometrics at the terminal. Commtrac resolves who they are and which account they approved, initiates the transfer on the local rail, and clears it into the merchant account.
Enrolled once, recognized everywhere
A customer who enrolls their biometrics at any Commtrac POS can pay at every Commtrac POS, with every bank account they choose to connect. There is nothing to carry and nothing to re enroll.
Presence is the credential
The payment is authorized by the customer standing at the terminal. There is no card number to skim, store, or test online, and no card network in the transaction at all.
The back office already knows
Every terminal ships with Commtrac Clearing at no charge, so the sale reaches order management, CRM and accounting systems the moment it initiates.
Worked example
Dinner in Toronto, 43.20 CAD
A customer finishes dinner and owes 43.20. They authenticate with biometrics at the terminal. An Interac e-Transfer leaves the account they linked and arrives in the restaurant’s own bank account in under ten seconds. No card is presented, no processor sits in the middle, and the restaurant keeps 43.18 of the 43.20.
What happens
The customer authenticates with biometrics at the terminal, at the table.
Commtrac recognizes them and the bank account they already approved.
An Interac e-Transfer leaves that account for the restaurant.
The restaurant’s own bank account is credited.
What never happens
No card is presented, tapped, or kept on file.
No card network, acquirer or processor takes a share of the bill.
The customer never types an email address, an account number or a memo.
Nothing is installed. There is no app on either side of the counter.
Deviceless, cardless checkout
The customer presents their biometrics, approves, and leaves. No card, no phone, no wallet, and nothing between their bank account and the merchant account except the domestic rail.
Link once, pay anywhere
Biometrics enrolled at one terminal work at every merchant running Commtrac POS, and a customer can hold multiple linked bank accounts behind the same signature.
Local rails, straight to the account
Sales settle over the domestic real time rail directly into the account the merchant already banks with. There is no processor balance, no batch schedule, and no one holding the funds in between.
A fixed fee, not a percentage
Settlement costs a flat fee in cents whatever the ticket. The same fee on a 40.00 lunch and on a 4,000.00 banquet, with no interchange and no volume tier negotiated over the merchant.
No chargeback surface
Real time rail payments are final when they move. With no card network in the transaction there is no chargeback mechanism to abuse, and with no card number there is nothing to steal.
Commtrac Clearing included
Each terminal comes with a Commtrac Clearing deployment free of charge, so instant confirmation, reconciliation and back office sync arrive with the hardware.
The route
Every middleman, itemized. Then removed.
A card sale is a queue of parties, and each one bills the merchant for its place in line. A Commtrac sale is one transfer between two bank accounts. Pick a party and read what it does on the card route, what it takes, and where it stands when the sale runs account to account.
Integration
What adoption looks like
Place the terminals
Each terminal arrives with Commtrac Clearing deployed at no charge. Set it on the counter, connect it, and the clearing side of every sale is already handled.
Connect the merchant account
Sales settle over the domestic real time rail directly into the bank account the business already holds. There is no processor account and no balance waiting to be paid out.
Wire in the back office
Order management, CRM and accounting systems connect through the included clearing deployment, so every sale reaches them the moment it initiates.
Customers enroll once
A customer links their bank and enrolls their biometrics at any terminal a single time, and enrollment is network wide, not per store. Someone who enrolled at another merchant walks into yours already recognized: they authenticate and pay.
Sell
The customer authenticates, the transfer moves account to account, and the sale clears for a flat fee. No percentage, no batch schedule, no waiting for your own money.
The network
Where the terminal sits
The Commtrac API
Deployable
The same account linking and payment initiation, delivered as an API for checkout on a page. What the terminal does at the counter, the API does online.
Commtrac Clearing
Deployable
Ships installed on every terminal at no charge for the software. Sales are confirmed, reconciled and posted to the back office the moment they move.
Commtrac Messaging
Scheduled release · Q2 2027
Steps in when the sale crosses borders. A Canadian paying at a terminal in the UK settles with Comtell, which syncs the cross border payment through to the merchant.
Featured paper
From Commtrac Foundations
 card networks and POSPaper 03
Paper 03 · Published August 2026
The Silent Partner Syndrome
Why every sale still pays a queue of middlemen first, and how Commtrac removes it
The route a card payment actually travels, priced: a record year of card fees against restaurant margins under three percent, a fee structure regulators’ own cost data cannot justify per ticket, and a fraud economy that exists because the credential is a stealable number. Then the sale without the queue.
Next step
Put Commtrac to work against your own volumes.
Tell us the rails you run and the institutions your customers bank with. We will walk through what it looks like on your existing stack, and what it costs at your volumes.
Contact sales
Global settlement infrastructure